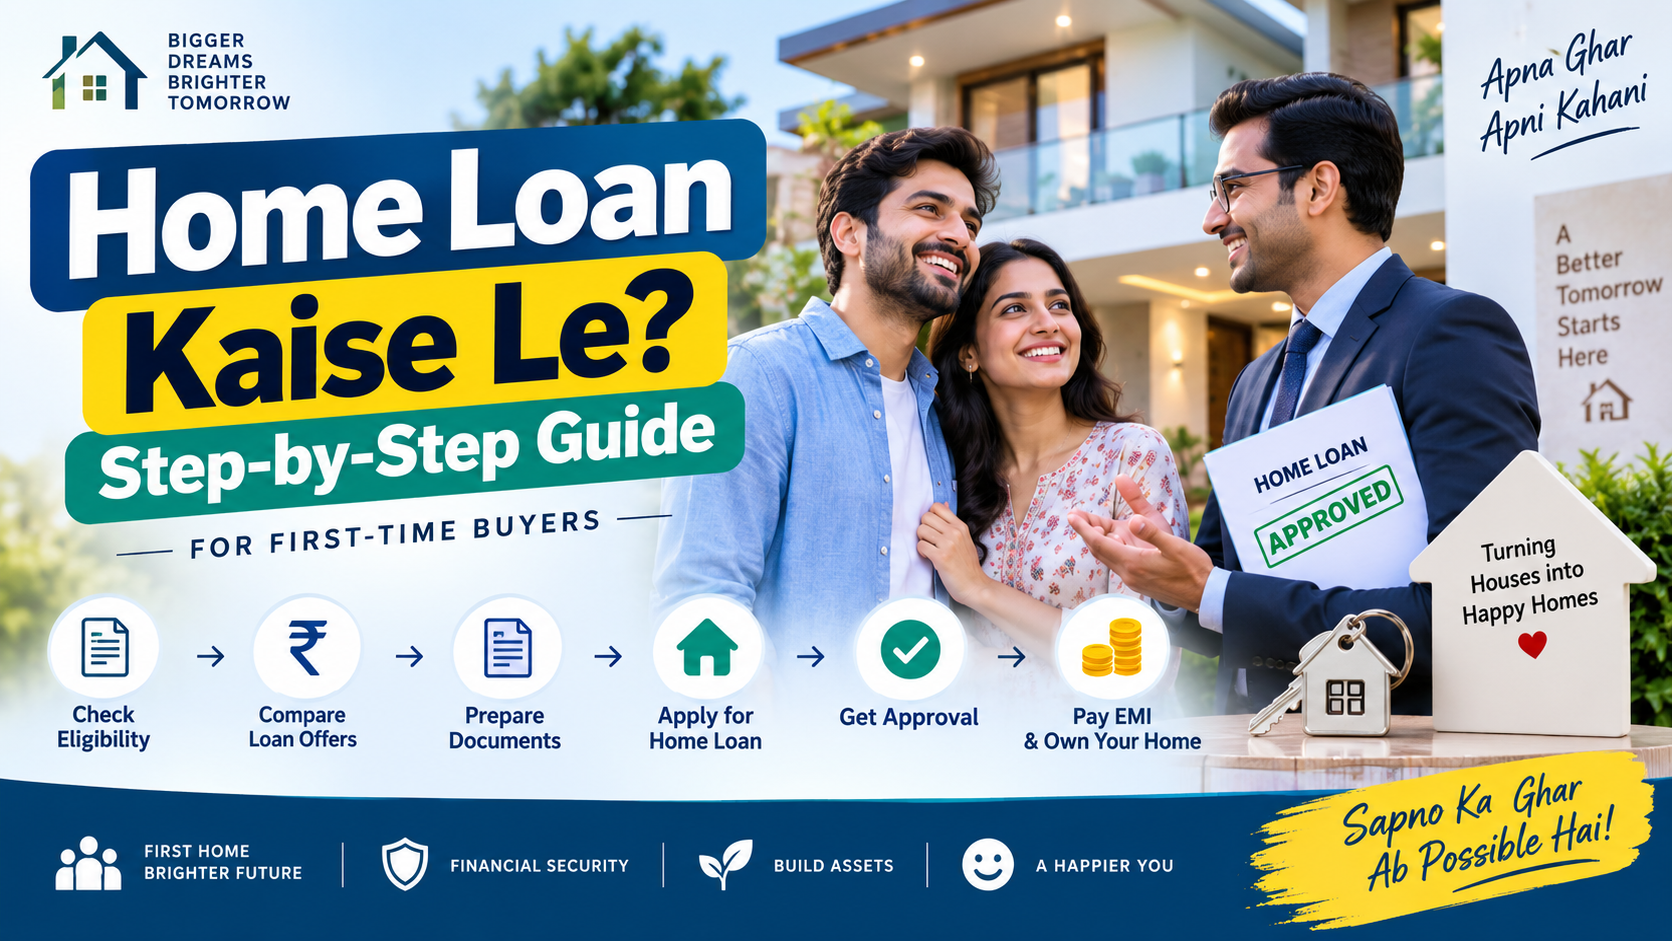

Home Loan Kaise Le? 12-Step Guide for First-Time Buyers
Home Loan Kaise Le? First-time buyer ke liye iska answer sirf loan application tak limited nahi hai. Aapko eligibility, CIBIL Score, documents, property verification, down payment, EMI, sanction aur disbursement sab samajhna chahiye.
Home loan generally residential property purchase, construction ya eligible home-related purpose ke liye liya ja sakta hai. This guide from Loan Enquiry For You explains the complete process in simple language.

Table of Contents
1. Home Loan Kya Hai Aur Kaise Kaam Karta Hai?
A home loan ek long-term secured loan hota hai jiska use residential property purchase, construction ya eligible home-related purpose ke liye kiya ja sakta hai. Home Loan Kaise Le samajhne ke liye simple example dekho. Suppose aap ₹50 lakh ka flat kharidna chahte ho, ₹10 lakh aapke paas savings hain aur remaining amount ke liye bank financing chahiye.
Lender aapki income, age, credit history, existing EMIs aur repayment capacity check karega. Saath hi property ki legal aur technical verification bhi ki ja sakti hai. Agar lender satisfied hai, eligible loan amount sanction ho sakta hai.
Home loan usually monthly EMIs me repay hota hai, jisme principal aur interest dono ka component hota hai. Current lender terms ka example dekhne ke liye official SBI Home Loan Terms check ki ja sakti hain. Property financing ka complete cost calculate karte waqt down payment, registration, stamp duty, processing fees, legal/technical cost, EMI aur maintenance sab include karo.
Loan approval ko personal budget mat samjho. Bank jitna approve kare aur aap jitna comfortably repay kar sako, dono alag numbers ho sakte hain.
2. Home Loan Ke Liye Kaun Apply Kar Sakta Hai?
Home loan salaried aur self-employed dono borrowers ke liye available ho sakta hai, subject to lender-specific eligibility. Salaried applicant ke case me lender monthly salary, employer profile, work experience, current job stability, existing EMIs aur retirement age evaluate kar sakta hai.
Self-employed applicant ke case me business income, business vintage, ITR, profit and loss statement, balance sheet aur bank transactions important ho sakte hain. Age bhi matter karti hai because home loan long-term commitment hota hai.
Co-applicant, where permitted, eligibility improve kar sakta hai if combined income considered hoti hai. Lekin co-applicant add karna automatic approval guarantee nahi karta.
Home Loan Kaise Le ka practical second step hai property final karne se pehle preliminary eligibility check karna. Agar aapko ₹60 lakh loan chahiye lekin profile ₹40 lakh ke around support karti hai, to property budget pehle hi adjust karna better hoga.
3. Home Loan Eligibility Kaise Calculate Hoti Hai?
Home-loan eligibility ka matlab hai lender aapko approximately kitna loan comfortably repayable maan sakta hai. Income important hai, lekin salary alone final eligibility decide nahi karti.
Common factors me age, net monthly income, employment/business stability, existing EMIs, credit score, requested tenure, property value aur eligible co-applicant income include ho sakte hain.
Suppose household income ₹1.2 lakh hai, existing EMI ₹15,000 hai aur proposed home EMI ₹45,000 hai. Total EMI burden ₹60,000 ho jayega. Lender internal policy ke according dekhega ki remaining income normal expenses aur future obligations ke liye sufficient hai ya nahi.
Home Loan Kaise Le ke time personal affordability calculation lender eligibility se bhi important hai. Food, medical costs, insurance, investments and emergency savings ko budget me include karo. Maximum eligible loan ko target mat banao; comfortable EMI ko target banao.
4. CIBIL Score Home Loan Me Kitna Important Hai?
CIBIL Score lender ko borrower ki past repayment behaviour samajhne me help karta hai. Good score generally stronger credit profile show karta hai, but score alone approval nahi deta.
Home Loan Kaise Le process me income, existing debt, repayment history aur requested EMI bhi important hote hain. Apply karne se pehle credit report me unknown loan, wrong overdue, closed account showing open ya incorrect late payment check karo.
Existing EMIs aur credit-card bills time par pay karo, unnecessary loan applications avoid karo aur card balances unnecessarily high mat rakho. Property booking ke baad nahi, booking se pehle credit health verify karna better hai.
Credit basics ke liye hamara Car Loan Minimum CIBIL Score guide bhi useful hai.
5. Home Loan Ke Liye Kaunse Documents Chahiye?
Home loan documentation detailed hota hai because lender ko borrower aur property dono verify karne hote hain. Common KYC documents me PAN, Aadhaar/acceptable OVD, passport, voter ID, driving licence aur photographs ho sakte hain depending on lender. Current home-loan eligibility and documentation information ke liye official ICICI Bank Home Loan page bhi refer ki ja sakti hai.
Salaried applicants se salary slips, bank statements, Form 16 aur tax-related documents maange ja sakte hain. Self-employed applicants se ITR, balance sheet, profit and loss account, bank statements and business proof maanga ja sakta hai.
Property documents me sale agreement, title documents, approved plans, allotment letter, builder papers, tax receipts ya other legal documents include ho sakte hain.
Home Loan Kaise Le ka smooth process chahiye to application se pehle name spelling, address, PAN and income records match kar lo. Inconsistency processing delay kar sakti hai.
6. Property Documents Aur Legal Verification Kyu Important Hai?
Home loan me borrower ki financial eligibility ke saath property ki legal quality bhi equally important hoti hai. Lender title, ownership chain, authorised construction, sanctioned plan, completion/occupancy documents where applicable, property tax status aur technical valuation check kar sakta hai.
Strong income and excellent CIBIL hone ke bawajood property title disputed hua to lender sanction ya disbursement hold kar sakta hai.
Home Loan Kaise Le me important rule ye hai: “bank loan de raha hai” ko independent legal due diligence ka replacement mat samjho. High-value property purchase me independent property lawyer se review karwana additional protection de sakta hai.
Under-construction project me builder approvals, construction stage and payment plan bhi check karo. Ready property me seller ownership and outstanding dues verify karo.
7. Home Loan Down Payment Kitni Karni Pad Sakti Hai?
Bank complete property cost finance kare, ye assume nahi karna chahiye. Borrower ko own contribution or down payment arrange karna pad sakta hai.
Suppose property price ₹50 lakh hai and loan sanctioned ₹40 lakh hai. Remaining ₹10 lakh borrower ko arrange karna hoga. Lekin down payment ke alawa stamp duty, registration, brokerage, processing fees, interiors and emergency fund bhi separately plan karo.
Higher down payment lower loan amount, lower EMI and lower total interest me help kar sakti hai. Lekin all savings down payment me use karna risky hai.
Home Loan Kaise Le ka safer formula: comfortable EMI + sufficient down payment + safe emergency fund. House purchase ke din savings zero nahi honi chahiye.
8. Home Loan Interest Rate Kaise Decide Hota Hai?
Home-loan interest rate borrower profile, credit score, loan amount, product type and prevailing benchmark structure par depend kar sakta hai. Floating-rate EMI loans aur borrower disclosures ke regulatory framework ko samajhne ke liye official RBI Regulations Handbook useful official resource hai. Loan fixed ya floating rate structure me available ho sakta hai.
Fixed rate agreed structure ke according more predictable ho sakti hai, while floating rate benchmark movements ke according change ho sakti hai.
Home Loan Kaise Le ke time sirf headline rate mat dekho. Annual rate, APR, benchmark, spread, reset frequency, switching charges, processing fee and prepayment conditions bhi compare karo.
Long tenure me small rate difference bhi significant total interest create kar sakta hai. Best lender sirf lowest advertised rate wala lender nahi, balki transparent total cost wala lender hai.
9. Home Loan EMI Kaise Calculate Hoti Hai?
Home-loan EMI mainly loan amount, interest rate and tenure par depend karti hai. Longer tenure EMI reduce kar sakta hai but total interest increase kar sakta hai. Shorter tenure EMI higher hoti hai but loan faster close hota hai.
First-time buyer ko “lowest EMI” trap se bachna chahiye. Correct question hai: kaunsa EMI comfortable hai and future goals ko damage nahi karta?
Home Loan Kaise Le ke time stress-test karo: agar rate increase ho, EMI thodi badh jaye ya income temporarily reduce ho jaye, kya household budget manage kar lega?
Monthly EMI ke baad insurance, investments, household expenses and emergency savings ke liye enough room rehna chahiye.
10. Home Loan Apply Karne Ka Complete Step-by-Step Process
Ab main question: Home Loan Kaise Le? Process ko simple steps me samjho:
1. Realistic property budget decide karo. 2. CIBIL report check karo. 3. Loan eligibility estimate karo. 4. Multiple regulated lenders compare karo. 5. Budget ke andar property shortlist karo. 6. Property documents verify karo. 7. KYC and income documents submit karo. 8. Lender credit assessment complete karega. 9. Property legal/technical verification hogi. 10. Sanction letter issue ho sakta hai. 11. Own contribution/down payment arrange karo. 12. Loan agreement carefully read and sign karo. 13. Conditions complete hone ke baad disbursement hoga. 14. Repayment schedule ke according EMI start karo.
Sanction letter, agreement, property papers, payment receipts and repayment schedule ki copies safely store karo.
11. Sanction Letter Aur Disbursement Me Kya Difference Hai?
Loan sanction and loan disbursement different stages hain. Sanction ka matlab lender ne borrower profile evaluate karke approved loan amount, tenure, rate and key conditions define ki hain. Borrowers ko loan amount, term, interest type, fees and other key facts clearly disclose karne ke RBI framework ka official Key Fact Statement format bhi useful reference hai.
Disbursement actual funds release hone ka stage hai. Isse pehle property legal verification, technical valuation, signed agreement, own contribution evidence and other security documents complete ho sakte hain.
Under-construction property me disbursement construction stages ke according parts me ho sakta hai. Ready property me payment seller ko agreed transaction structure ke according release ki ja sakti hai.
Home Loan Kaise Le ke time sanction letter ko final money transfer mat samjho. Seller or builder payment schedule ko lender disbursement timeline ke saath coordinate karo.
12. First-Time Home Buyers Ko Kaunsi Mistakes Avoid Karni Chahiye?
First-time buyers ko kuch common mistakes avoid karni chahiye:
– Maximum eligible loan automatically mat lo. – Emergency fund completely use mat karo. – Sirf low EMI dekhkar very long tenure mat choose karo. – CIBIL last moment par mat check karo. – Property papers blindly trust mat karo. – Sirf interest rate compare mat karo. – Floating-rate risk ignore mat karo. – Sanction ko disbursement mat samjho. – Loan agreement bina samjhe sign mat karo. – Future financial goals ignore mat karo.
Home Loan Kaise Le ka final rule simple hai: best home loan wo nahi jo maximum amount de, balki wo hai jo ghar lene ke baad bhi aapko financially comfortable rakhe.
Home Loan Kaise Le: Quick Checklist
| Step | What to Check |
|---|---|
| Budget | Comfortable EMI and down payment |
| Eligibility | Income, age, debt and credit profile |
| Documents | KYC, income and property papers |
| Property | Legal and technical verification |
| Rate | Fixed/floating, APR and fees |
| Sanction | Amount, tenure and conditions |
| Disbursement | Actual release of funds |
Frequently Asked Questions
Home Loan Kaise Le for a First-Time Buyer?
Budget decide karein, eligibility and CIBIL check karein, lenders compare karein, property documents verify karein, application submit karein and sanction/disbursement conditions complete karein.
Home Loan Ke Liye CIBIL Score Important Hai?
Yes. Credit score lender ko repayment history samajhne me help karta hai, but final approval income, existing debt and property assessment par bhi depend karta hai.
Sanction Aur Disbursement Same Hote Hain?
No. Sanction approval stage hai, while disbursement actual funds release hone ka stage hai after required conditions are completed.
Conclusion: Home Loan Kaise Le Safely?
Home Loan Kaise Le? Sabse safe approach hai property search se pehle budget aur comfortable EMI decide karna. Uske baad CIBIL, eligibility and lender comparison karo.
Property final hone ke baad legal and technical documents carefully verify karo. Down payment ke saath registration and emergency expenses ke liye cash reserve rakho.
Most importantly, EMI ko maximum capacity tak push mat karo. Home loan long-term commitment hai and it should comfortably coexist with emergency savings and future financial goals.
Disclaimer
This article is for general informational and educational purposes only and should not be treated as financial, investment, tax or legal advice or as a guarantee of home-loan approval. Eligibility criteria, interest rates, LTV limits, documentation requirements, fees and lender policies can change. Property laws and documentation requirements can vary by location and transaction. Always verify the latest details directly with the relevant regulated bank or housing finance company and consider independent legal advice before purchasing a property.

Pingback: Home Loan Eligibility: 10 Important Factors to Calculate It