
Car Loan Down Payment: 5 Important Things You Should Know
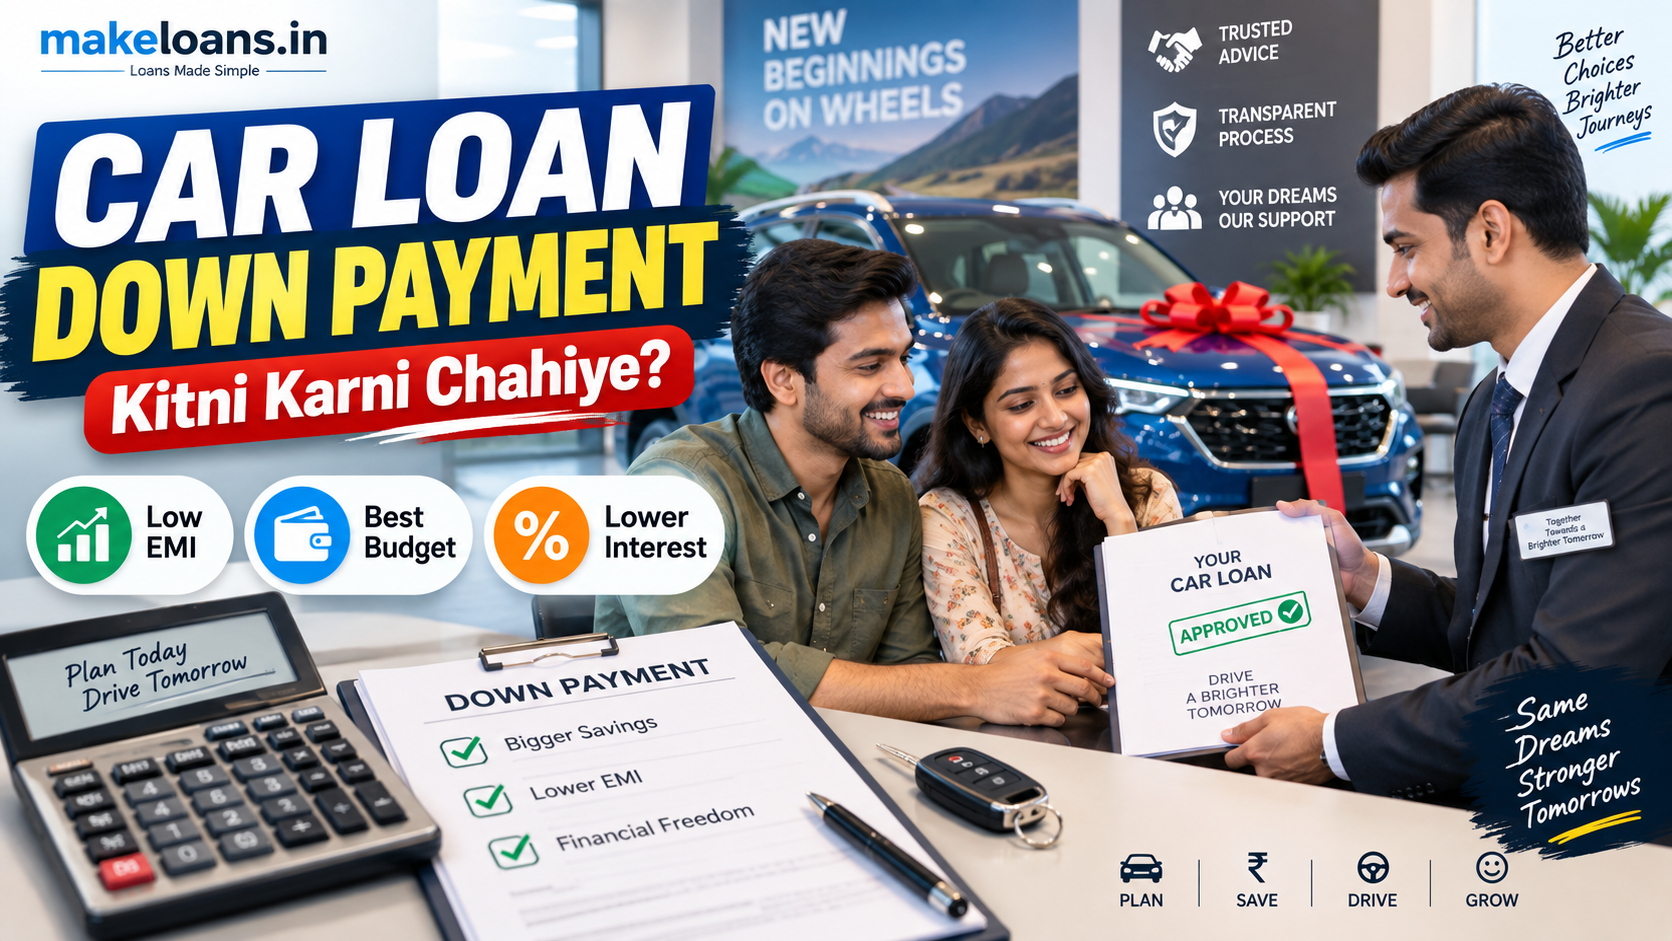
Car Loan Down Payment kitni karni chahiye? Iska answer sirf ek fixed percentage se nahi diya ja sakta. Lender funding policy, car price, LTV, loan eligibility aur aapki own savings milkar ideal down payment decide karte hain.
Down payment car loan ki EMI, total interest aur monthly debt burden ko directly affect karti hai. This guide from Loan Enquiry For You explains minimum contribution, higher down payment ke benefits, ideal amount aur common mistakes in simple language.

Table of Contents
1. Car Loan Down Payment Kya Hoti Hai?
Car Loan Down Payment wo amount hoti hai jo borrower vehicle purchase ke time apne funds se pay karta hai. Remaining eligible amount lender finance karta hai.
Suppose car ki on-road price ₹10 lakh hai aur lender ₹8.5 lakh finance karta hai. Remaining ₹1.5 lakh aapko apni taraf se arrange karna hoga. Ye amount aapki down payment ya own contribution mani ja sakti hai.
Different lenders different funding ratios offer kar sakte hain. SBI ke published Auto Loan terms me maximum LTV 85% of on-road price aur maximum loan amount up to 100% of ex-showroom price ka framework diya gaya hai. Current lender-specific details ke liye official SBI Auto Loan Terms check ki ja sakti hain.
Some lenders selected schemes me higher financing bhi offer kar sakte hain. Isliye dealership ke “zero down payment” ya “100% finance” statement ko universal rule nahi samajhna chahiye.
Final down payment actual sanction, vehicle price aur lender policy ke basis par decide hoti hai. Car book karne se pehle official financing amount confirm karna safer hai.
2. Minimum Down Payment Kitni Ho Sakti Hai?
Minimum Car Loan Down Payment lender ke Loan-to-Value ratio aur final sanctioned loan amount par depend karti hai.
Agar lender on-road price ka 85% finance karta hai, to simplified example me borrower ko remaining 15% apni taraf se arrange karna pad sakta hai. Lekin ye percentage har bank ya NBFC par apply nahi hoti.
Kuch lenders selected borrowers ko much higher funding offer kar sakte hain. HDFC Bank ki car-loan guidance me bhi higher financing options ke examples milte hain, subject to eligibility and scheme conditions. Current information ke liye official HDFC Bank New Car Loan page check karein.
Suppose car on-road price ₹12 lakh hai. Agar lender ₹10 lakh sanction karta hai, borrower ko around ₹2 lakh own contribution arrange karna hoga. Agar sanctioned amount ₹11.5 lakh hai, down payment much lower ho jayegi.
Best approach ye hai ki large booking payment se pehle written or official loan eligibility aur funding amount confirm karein.
3. Higher Down Payment Karne Ke Kya Fayde Hain?
Higher Car Loan Down Payment ka biggest benefit lower loan principal hota hai. Loan amount kam hoga to monthly EMI aur total interest dono reduce ho sakte hain.
Suppose car price ₹10 lakh hai. Option A me aap ₹1 lakh down payment karke ₹9 lakh borrow karte ho. Option B me ₹3 lakh down payment karke ₹7 lakh borrow karte ho.
Same interest rate aur tenure par ₹7 lakh loan ki EMI lower hogi because principal ₹2 lakh kam hai.
- Lower loan amount
- Lower monthly EMI
- Lower total interest
- Lower debt burden
- More monthly financial flexibility
Lekin higher down payment ka matlab sari savings car me laga dena nahi hai. Car purchase ke baad fuel, insurance, servicing, tyres aur emergency repairs ke liye cash buffer chahiye.
Complete car-loan process ke liye hamara Car Loan Kaise Le guide bhi dekhein.
4. Kitni Down Payment Ideal Ho Sakti Hai?
Ideal Car Loan Down Payment ka koi one-size-fits-all percentage nahi hai. Best amount wo hai jo EMI ko comfortable reduce kare without emptying your emergency savings.
Suppose lender 90% financing offer kar raha hai. Technically aap 10% down payment karke car le sakte ho. Lekin agar 20–25% comfortably pay kar sakte ho aur emergency fund safe rehta hai, to smaller loan long-term me easier ho sakta hai.
Decision se pehle three questions puchhein:
- Down payment ke baad emergency fund kitna bachega?
- New EMI monthly income me comfortably fit hogi?
- Higher down payment se total interest kitna reduce hoga?
Sirf isliye 100% finance lena zaroori nahi hai kyunki lender offer karta hai. Likewise, EMI reduce karne ke liye all savings use karna bhi smart strategy nahi hai.
Ideal formula simple hai: lower debt + manageable EMI + sufficient savings.
5. Down Payment Karte Waqt Kaunsi Galtiyan Avoid Karein?
Car Loan Down Payment plan karte waqt sabse common mistake complete savings use kar dena hai.
Car loan sanction hone ke baad bhi ownership expenses continue rehte hain. Fuel, insurance, servicing, tyres, battery aur household emergencies ke liye funds chahiye.
Second mistake down payment ke liye high-interest personal loan ya credit card use karna hai. Agar car loan relatively lower rate par hai but down payment expensive unsecured borrowing se aati hai, total financing cost unnecessary increase ho sakti hai.
Third mistake sirf dealership ki low EMI quote dekhna hai. Lower EMI longer tenure se achieve ki ja sakti hai, but total interest higher ho sakta hai.
Fourth mistake written sanction se pehle large non-refundable booking amount pay kar dena hai. Final lender funding expected amount se lower hui to additional cash arrange karna difficult ho sakta hai.
Simple rule: as much as comfortably affordable, but not so much that your emergency savings disappear.
Car Loan Down Payment: Quick Comparison
| Down Payment Level | Possible Effect |
|---|---|
| Low | Higher loan amount and EMI |
| Moderate | Balanced EMI and savings |
| High | Lower EMI and interest, but check emergency fund |
Frequently Asked Questions
Is 20% Car Loan Down Payment Good?
It can be a practical amount for some borrowers, but there is no universal ideal percentage. Check whether EMI becomes comfortable while emergency savings remain safe.
Can I Buy a Car with Zero Down Payment?
Some lenders or schemes may offer very high financing to eligible borrowers, but zero down payment is not guaranteed for every applicant or vehicle.
Does Higher Down Payment Reduce EMI?
Yes. A higher own contribution reduces the loan principal, which can lower the monthly EMI when interest rate and tenure remain the same.
Should I Use All My Savings for Down Payment?
No. Maintain an emergency fund for insurance, servicing, repairs and household expenses even after purchasing the car.
Conclusion: Car Loan Down Payment Kitni Karni Chahiye?
Car Loan Down Payment ka exact amount lender, car price, funding ratio aur borrower eligibility par depend karta hai.
Higher down payment EMI aur total interest ko reduce kar sakti hai, but emergency savings ko completely exhaust nahi karna chahiye.
Best down payment wo hai jo loan amount reduce kare, EMI comfortable rakhe aur sufficient savings safe rakhe.
For more information, read our Car Loan Kaise Le, Car Loan Minimum CIBIL Score and New Car Loan vs Used Car Loan guides.
Disclaimer
This article is for general informational and educational purposes only and should not be treated as financial advice or a guarantee of loan approval. Car-loan funding percentages, LTV rules, interest rates and lender policies can change. Always verify the latest terms directly with the relevant regulated bank, NBFC or lender before applying.