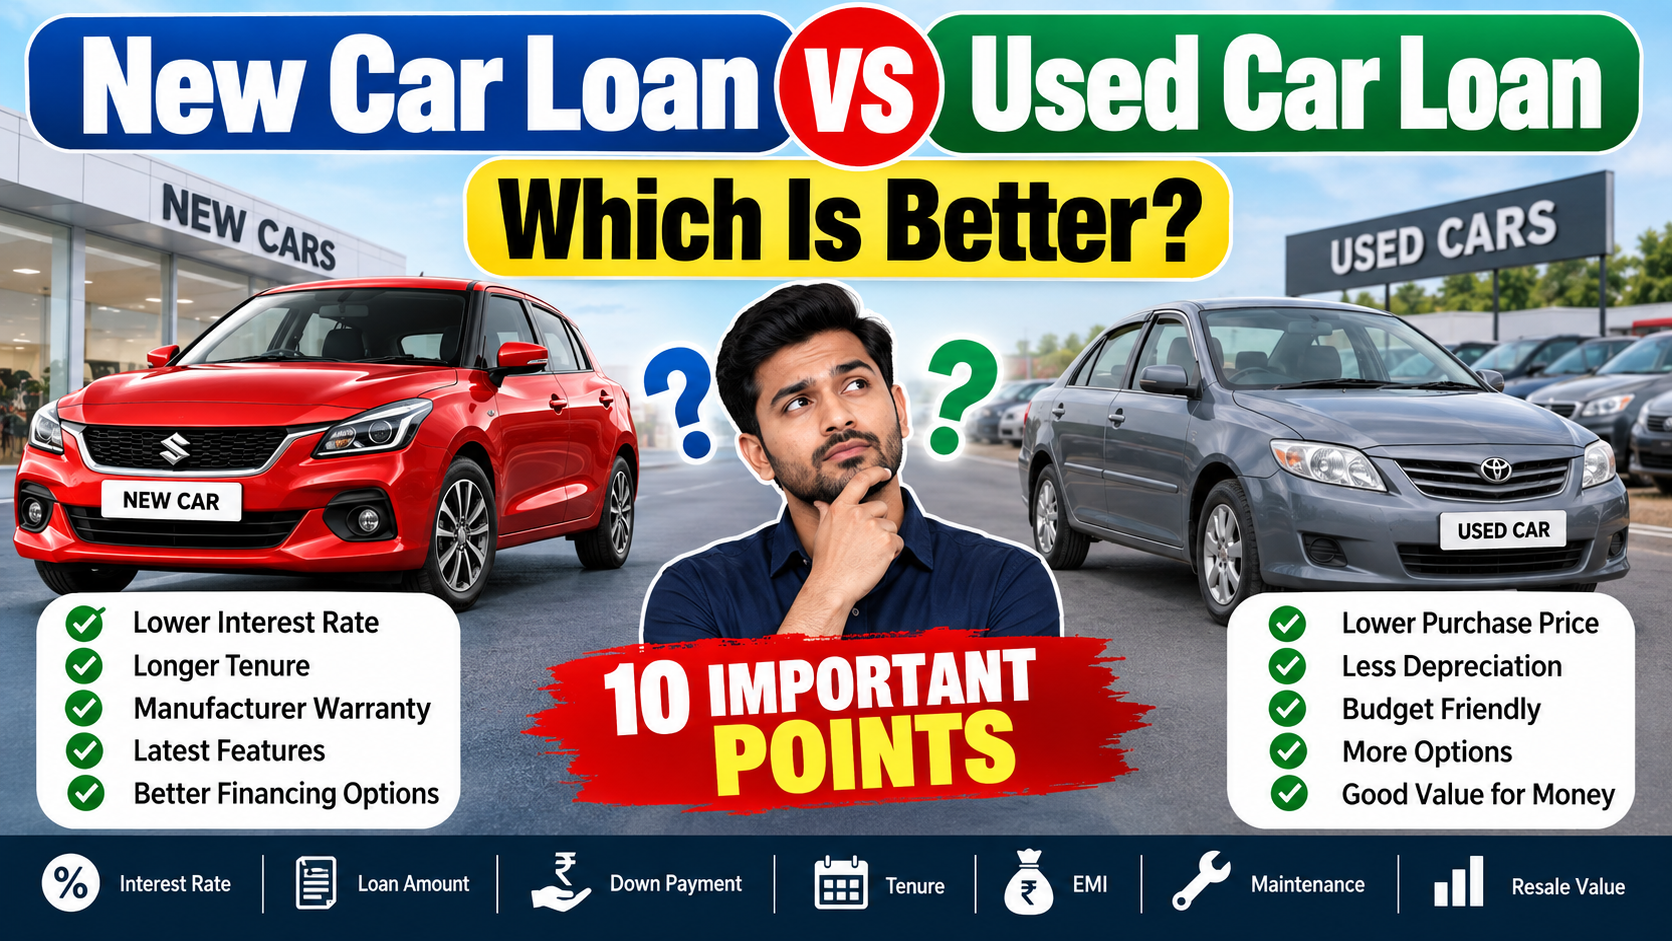

New Car Loan vs Used Car Loan: 10 Important Differences
New Car Loan vs Used Car Loan comparison tab important ho jata hai jab aap car finance karne wale hote hain. New car financing relatively straightforward ho sakti hai, jabki used car loan me vehicle age, condition, valuation aur ownership history zyada important ho sakti hai.
Sirf car ki purchase price compare karna enough nahi hai. Interest rate, down payment, EMI, tenure, insurance, maintenance aur resale value milkar total ownership cost decide karte hain. This guide from Loan Enquiry For You explains the complete comparison in simple language.

Table of Contents
1. New Car Loan Aur Used Car Loan Me Basic Difference Kya Hai?
New Car Loan vs Used Car Loan ka sabse basic difference vehicle ki condition aur valuation hai. New car loan brand-new vehicle purchase ke liye hota hai, while used car loan pre-owned or already registered vehicle purchase ko finance karta hai.
New car ki ex-showroom aur on-road price dealer invoice se clearly establish hoti hai. Lender ko vehicle condition assess karne ki zarurat comparatively kam hoti hai because the vehicle is new.
Used car financing me lender ko current market value, manufacturing year, registration age, condition aur ownership history ko zyada closely evaluate karna pad sakta hai.
ICICI Bank pre-owned car financing ko separately structure karta hai. Current details ke liye official ICICI Car Loan page check ki ja sakti hai.
Final choice budget, vehicle condition, monthly income aur total ownership plan ke according hona chahiye.
2. Interest Rate Kis Loan Me Kam Ho Sakta Hai?
Generally new-car loan ki interest rate used-car loan se lower ho sakti hai. New vehicle lender ke liye easier-to-value asset hota hai, while used car me condition and resale uncertainty zyada ho sakti hai.
New Car Loan vs Used Car Loan compare karte waqt headline rate ke saath total rupee interest ko bhi dekhna chahiye.
Suppose new car loan amount ₹10 lakh hai aur used car loan amount ₹6 lakh. Used-car rate slightly higher hone ke bawajood smaller principal ki wajah se total interest lower ho sakta hai.
- Loan amount
- Interest rate
- Tenure
- Processing fee
- Total interest
- Total repayment
Advertised starting rate sab borrowers ko automatically nahi milta. Final rate borrower profile, credit history aur lender policy par depend kar sakta hai.
Credit profile samajhne ke liye hamara Car Loan Ke Liye Minimum CIBIL Score guide useful hai.
3. Loan Amount Aur LTV Me Kya Difference Hota Hai?
New-car financing commonly ex-showroom or on-road price se linked hoti hai. Used-car loan me lender current assessed vehicle value ko zyada importance de sakta hai.
New Car Loan vs Used Car Loan me ye difference important hai because seller ki asking price aur lender valuation same hona necessary nahi hai.
Suppose seller used car ke liye ₹8 lakh maang raha hai, but lender vehicle value ₹7 lakh assess karta hai. Financing lender-assessed value ke basis par calculate ho sakti hai.
LTV ka meaning Loan-to-Value ratio hai. Lender vehicle value ke against kitna percentage finance karega, ye LTV se linked ho sakta hai.
Maximum funding figure ko guaranteed sanction na samjhein. Actual sanction borrower income, CIBIL, existing debt aur lender policy par depend karega.
4. Down Payment New Car vs Used Car Me Kitni Ho Sakti Hai?
Down payment wo amount hai jo borrower car purchase ke time apne funds se pay karta hai. Required amount final sanctioned loan aur vehicle price ke according change hota hai.
New Car Loan vs Used Car Loan me used car ke case me valuation gap down payment ko unexpectedly increase kar sakta hai.
Example: seller price ₹7 lakh hai, but lender assessed value ₹6 lakh. Agar lender ₹6 lakh value ke against financing calculate karta hai, purchase price ka remaining portion borrower ko arrange karna pad sakta hai.
Higher down payment ka benefit lower loan principal, lower EMI and potentially lower total interest ho sakta hai.
Lekin sari savings down payment me use karna risky hai. Used car especially tyres, battery, service ya repairs ke liye emergency cash demand kar sakti hai.
5. Loan Tenure Kis Option Me Longer Ho Sakta Hai?
Historically new-car loans me longer repayment tenure common raha hai because vehicle new hota hai and expected usable life longer hoti hai.
Lekin current market me used-car products bhi relatively long tenures offer kar sakte hain, depending on lender and vehicle age.
New Car Loan vs Used Car Loan compare karte waqt tenure ko sirf monthly EMI reduce karne ka tool na samjhein.
Long tenure ka benefit lower monthly EMI hai. Downside higher total interest and longer debt period ho sakta hai.
Used-car loan me additional question hai: kya vehicle itni long tenure tak reliable rahega? Agar already 5-year-old car par 6-year loan liya, loan end hone tak vehicle 11 years old ho sakti hai.
Complete tenure planning ke liye hamara Car Loan Kaise Le guide bhi dekhein.
6. Used Car Ki Age Aur Condition Loan Approval Ko Kaise Affect Karti Hai?
Used car loan me vehicle khud credit assessment ka important part ban jata hai. New car me condition known hoti hai, but used car me market value aur mechanical condition vary kar sakti hai.
New Car Loan vs Used Car Loan ke used-car side me manufacturing year, registration year, kilometres driven, ownership history, accident history and service records important ho sakte hain.
- Manufacturing year
- Registration age
- Kilometres driven
- Service history
- Accident history
- Number of previous owners
- Current resale value
Older vehicle ki assessed value lower ho sakti hai, which can reduce sanctioned loan amount or available tenure.
Lender approval mechanical quality certificate nahi hai. Used car purchase se pehle independent mechanic inspection karwana smart step hai.
7. EMI New Car Loan vs Used Car Loan Me Kaise Compare Karein?
EMI comparison me sirf monthly amount dekhna misleading ho sakta hai. New car price higher ho sakti hai, so principal larger ho sakta hai. Used car cheaper ho sakti hai but financing rate higher ho sakti hai.
New Car Loan vs Used Car Loan me correct comparison monthly EMI + total interest + down payment + ownership costs ka hona chahiye.
| Factor | New Car | Used Car |
|---|---|---|
| Purchase Price | Usually higher | Usually lower |
| Loan Principal | Can be higher | Can be lower |
| Interest Rate | Can be lower | Can be higher |
| Repair Risk | Usually lower initially | Can be higher |
Longer tenure EMI reduce karega but total interest increase kar sakta hai. Isliye “EMI kitni hai?” se zyada important question hai “complete tenure me total kitna repay karna hai?”
8. Insurance, Maintenance Aur Repair Cost Kis Me Zyada Hogi?
Loan ke bahar ke expenses bhi New Car Loan vs Used Car Loan decision ko strongly affect karte hain.
New car usually manufacturer warranty ke saath aati hai, so initial years me major repair risk comparatively lower ho sakta hai.
Used car ka purchase price lower ho sakta hai, but maintenance requirements higher ho sakti hain.
- Tyres
- Battery
- Brake components
- Suspension
- AC repair
- Major servicing
Insurance premium vehicle value and age ke according differ kar sakti hai. Used car me previous claim history bhi check karna useful hai.
Sometimes slightly higher new-car EMI predictable maintenance ke saath easier ho sakti hai compared with lower used-car EMI plus frequent repair bills.
9. Resale Value Aur Depreciation Me Kya Difference Hai?
New car early ownership years me faster depreciation face kar sakti hai. Purchase ke shortly after resale value noticeably fall ho sakti hai.
Used car initial depreciation ka significant portion already absorb kar chuki hoti hai. Ye used vehicle ka major financial advantage ho sakta hai.
New Car Loan vs Used Car Loan me depreciation especially important hai if you plan to sell the car after 3–5 years.
- Brand resale reputation
- Model demand
- Vehicle age
- Mileage
- Service record
- Ownership count
- Accident history
Very old used vehicle automatically better value nahi hai. Maintenance risk and weak resale demand financial advantage reduce kar sakte hain.
10. New Car Loan vs Used Car Loan: Aapke Liye Kaunsa Better Hai?
New Car Loan vs Used Car Loan ka koi universal winner nahi hai.
New car loan better ho sakta hai if you want:
- Brand-new vehicle
- Manufacturer warranty
- Predictable maintenance
- Latest features and safety
- Potentially better financing rate
- Long ownership period
Used car loan better ho sakta hai if you want:
- Lower purchase price
- Smaller loan amount
- Lower initial depreciation hit
- Better model within limited budget
Final decision ke liye purchase price, down payment, loan interest, processing fee, insurance, maintenance, expected repairs and resale value calculate karein.
New Car Loan vs Used Car Loan: Quick Comparison
| Feature | New Car Loan | Used Car Loan |
|---|---|---|
| Vehicle Price | Higher | Lower |
| Interest Rate | Can be lower | Can be higher |
| Valuation | Dealer invoice based | Assessed market value important |
| Maintenance | Usually lower initially | Can be higher |
| Depreciation | Higher in early years | Initial depreciation already absorbed |
| Warranty | Usually available | Depends on vehicle |
Frequently Asked Questions
Is New Car Loan Cheaper Than Used Car Loan?
New-car loans can have lower financing rates, but the vehicle price is usually higher. Compare total interest and total ownership cost rather than rate alone.
Can Used Car Loan EMI Be Lower?
Yes. Used car ki purchase price and loan principal lower ho sakte hain, which can reduce EMI even when the interest rate is slightly higher.
Does Used Car Age Affect Loan Approval?
Yes. Vehicle age, condition and valuation sanctioned amount and tenure ko affect kar sakte hain depending on lender policy.
Which Loan Is Better for a First-Time Car Buyer?
It depends on budget. A reliable used car can reduce purchase cost, while a new car can offer warranty and predictable maintenance. Compare full ownership cost.
Should I Take a Long Loan on an Old Used Car?
Be careful. Long tenure on an already old car can mean paying EMI while maintenance expenses rise and resale value falls.
Conclusion: New Car Loan vs Used Car Loan – Which Should You Choose?
New Car Loan vs Used Car Loan decision sirf interest rate se nahi hona chahiye. New car better financing, warranty and predictable maintenance provide kar sakti hai. Used car lower purchase price and lower initial depreciation advantage de sakti hai.
Before finalising, compare loan amount, interest rate, down payment, EMI, tenure, insurance, maintenance and expected resale value.
For more car-loan information, read our Car Loan Kaise Le guide and Car Loan Minimum CIBIL Score guide.
Disclaimer
This article is for general informational and educational purposes only and should not be treated as financial advice or a guarantee of loan approval. Interest rates, funding limits, loan tenure, eligibility criteria and lender policies can change. Always verify the latest terms directly with the relevant regulated bank, NBFC or lender before applying for a new or used car loan.